

Corporate Actions - Main Board ListCos – various sections, commentary and legend
CAs effected by ListCos require compliance, inter alia, with both the JSE LR and the Cos Act (collectively referred to as “Both”).
Director approval of a CA is the same for Both, i.e. an approved directors’ resolution.
Announcements will be either SENS only or SENS and the press. Announcements on SENS will be in long form in English, disclosing all required matters in terms of the JSE LR and the Companies Act. Announcement in the press, where required in terms of the JSE LR, or voluntarily if ListCo so desires, allows for a summarised short form of the long form SENS announcement to be published in one widely distributed newspaper, in any one official language with relevant warnings concerning the summarised nature of the announcement.
If a CA requires a circular to be issued to shareholders, the content of the circular must be in compliance with the JSE LR and must be approved by the JSE via three electronic submissions to the JSE (informal comment, informal approval and formal approval).
If a CA requires approval by shareholders, the circular will include a notice of GM unless it is being effected in an AGM, in which case the notice is in respect of an AGM. The notice will contain the relevant required resolution(s). Voting includes shareholders present in person or by proxy representation. A CA may require more than one resolution in which case the notice will include all relevant resolutions. If each resolution is mutually exclusive of the other resolutions, then it is contemplated that some may be passed, and some may fail. If, however, a CA requires two separate shareholder resolution approvals in terms of the Cos Act and JSE LR, respectively, in order for the CA to become unconditional and be capable of implementation, the two resolutions will then be structured on an inter‑conditional basis so that if one fails, they both fail, thus preventing a conflict of laws. Furthermore, a resolution may require structuring in order not to allow certain shareholders to vote on such resolution because they are considered to be “tainted”, resulting in an “independent” shareholder vote. This is commonly applicable with regard to the JSE LR and Takeover Law and less so with regard to Chapters 1 to 4 of the Cos Act.
Any documents lying for inspection will be available at ListCo’s registered office or electronically (probably on the website or via email) – as provided by ListCo and as elected by the person concerned.
Fairness opinions
If a JSE LR CA requires a fairness opinion (“FO”) from the ListCo independent non‑executive directors (“iNEDs”) to be issued to ListCo shareholders it will be described as an “iNED FO”. If a JSE LR CA requires a FO from an IPEx to be issued to ListCo shareholders by ListCo, it will be described as an “IPEx FO” i.e. in the case of a termination of listing at the instance of the issuer. An IPEx FO must comply with Schedule 5 of the JSE LR (“Schedule 5”). An iNED FO will consider the same valuation and pricing metrics as an IPEx FO. ListCo’s Board will issue its recommendation, taking account of either an iNED FO or an IPEx FO. If a CA requires an iNED FO, it is acceptable for ListCo’s Board to elect to obtain a Schedule 5 compliant IPEx FO instead. While it is possible for a Board to disagree with an IPEx FO, it is not possible for a Board to disagree with an iNED FO.
The purpose of an iNED FO or IPEx FO is to provide information to ListCo shareholders to enable them to make an informed decision concerning any required action to be taken regarding a particular CA. Schedule 5 IPEx FOs scopes in value and price together, which is acceptable if a CA does not need to separate value per share from price per share. If a CA is being effected in compliance with Takeover Law or both the JSE LR and Takeover Law together, then the principles in Takeover Law are applicable to the FO and the IPEx FO becomes a “fair and reasonable” opinion (“IPEx F+RO”) with a separate opinion on a value range dealt with by the “fair” opinion and a separate opinion on price dealt with by the “reasonable” opinion. If a JSE LR CA requires value per share and price per share to be considered separately, then an IPEx F+RO will be required.
Pre‑listing statements and revised listing particulars
If an initial listing application or an acquisition issue of securities by an existing ListCo requires the issuance of a PLS or RLP, such issuance will be in standalone PLS form for an initial listing and will be attached to an acquisition circular as RLP for an existing ListCo.
Solvency and liquidity test and working capital statements
A CA may require a solvency and liquidity test (“SLT”) to be performed by ListCo with regard to the Cos Act for certain “impoverishment” CAs. The equivalent JSE LR is a working capital statement (“WCS”). Both SLT and WCS require the ListCo Board to be satisfied that post a CA, the fairly valued assets of the ListCo group will exceed the fairly valued liabilities of the ListCo group (“solvency test”), and that ListCo will be able to settle all known liabilities in the next 12-month period (“liquidity test”).
Takeover Law compliance
Certain CAs also trigger Takeover Law requirements in Chapter 5 of the Cos Act. The two types of CA that trigger Takeover Law are, firstly, Fundamental Transactions (being Section 112 disposals of the majority or more of ListCo’s fairly valued gross or net assets, Section 113 amalgamations or mergers and Section 114 schemes of arrangement) and secondly, any other CA giving rise to an actual change of shareholder control (affected transaction triggering a Mandatory Offer) or possible change of shareholder control (general offer triggering a proposed affected transaction) of ListCo. Takeover Law transactions (usually) require the issuance of an IPEx F+RO plus an independent Board opinion. Fundamental Transactions require a special resolution to be approved by shareholders, upon which an offeror and concert parties may not vote, i.e. taint is applied to ensure only “independent” shareholders vote.
It is beyond the scope of this summary of CAs to deal with Takeover Law in any detail. Interested persons are referred to Commentary on South African Takeover Law (4th Ed.) authored by KA Rayner and RJ Connellan.
Narrative summary
The CA tables summarise compliance with the JSE LR, Chapters 1 to 4 of the Cos Act and Takeover Law (Chapter 5 of the Cos Act). Reference to the Cos Act must be read to include compliance with any foreign corporate law(s) applicable to foreign‑domiciled primary ListCos. Certain compliance requirements are explained and defined in the CA tables, but the following defined compliance requirements are provided as they are “generic” in nature.
Resolutions
- An ordinary resolution requiring >50% shareholder approval with all shareholders being able to vote is described as “OR >50% all vote”;
- An ordinary resolution requiring >50% shareholder approval with participating shareholders and associates being unable to vote is described as “OR >50% ind vote”;
- An ordinary resolution requiring 75% or more shareholder approval with all shareholders being able to vote is described as “OR 75%+ all vote”;
- An ordinary resolution requiring 75% or more shareholder approval with an offeror, concert parties, participating shareholders and/or associates being unable to vote is described as “OR 75%+ ind vote”;
- A special resolution requiring 75% or more shareholder approval with all shareholders being able to vote is described as “SR 75%+ all vote”; and
- A special resolution requiring 75% or more shareholder approval with participating shareholders and associates being unable to vote is described as “SR 75%+ ind vote”.
Change of control
- A CA giving rise to “change of control” (“Change of Control”) of a ListCo effected by a subscriber (issue for cash), underwriter (rights offer) or asset vendor (acquisition issue to settle assets acquired by ListCo) subscribing for ListCo voting shares resulting in 35%+ voting power control for such person of ListCo (“Controlling Shareholder”) gives rise to the Takeover Law requirement of the Controlling Shareholder having to make a Mandatory Offer to all “minority” shareholders of ListCo (excluding Controlling Shareholder and concert parties) at the highest price paid in achieving control measured in terms of a look-back period of six months prior to an “offer period” commencing (“Mandatory Offer”); and
- A CA involving a possible/probable Change of Control may be structured to avoid a Mandatory Offer by incorporating a condition in the CA whereby ListCo obtains (independent) “minority” shareholder approval in GM = OR >50% ind vote – either prior to the CA being effected or as part of the CA resolution approvals – in GM – waiving the requirement for a Mandatory Offer subject to Takeover Regulation Panel (“TRP”) approval thereto – which is assumed as being obtained (“Waiver Approval”).
Abbreviations
- IFS = condensed consolidated Interim Financial Statements for the first six months of FYE (short from);
- Second IFS = reviewed condensed consolidated IFS for 12 months of FYE after extension of FYE (short form);
- Cons AFS = audited consolidated AFS (long form);
- Cond AFS = reviewed/audited condensed consolidated AFS (short form);
- Summary AFS = audited (extracted) condensed consolidated AFS (short form);
- Co AFS = audited company AFS (long from);
- AR = Annual Report;
- SLT passed = solvency and liquidity test in terms of Section 4 of the Cos Act has been passed;
- WCS = JSE working capital statement – same requirements as the SLT;
- Cat 1 or Cat 2 = Category 1 or Category 2 acquisition/disposal transaction effected by the ListCo group in terms of Section 8 (and Section 9 if effected with a RP) unless exempt in terms of complex requirements in Section 8 (read with Section 9);
- iNED FO = fairness opinion in terms of the JSE LR;
- IPEx FO = fairness opinion in terms of the JSE LR where an IPEx is opining;
- IPEx F+RO = fair and reasonable opinion in terms of Takeover Law. The consideration offered is measured against the share price at date of first announcement (“Share Price”) and against a fair value range (“Value Range”) – if the consideration is greater than the Share Price, the opinion will state that it is “reasonable” and if the consideration is greater than the lowest level of the Value Range, the opinion will state that it is “fair”;
- FO = collective reference to an iNED FO or IPEx FO or IPEx F+RO;
- Controlling Shareholder = shareholder (including associates and concert parties) that exercises =/>35% voting power in GM/AGM or can appoint/remove directors on ListCo’s Board that exercise =/>35% voting power in Board meetings;
- Material Shareholder = shareholder holding currently – or in the last 12 months held – either a 10% (prime segment) or 20% (general segment) beneficial interest in ListCo securities or ListCo’s holding company’s securities (“H Co”) i.e. measured at two levels on an either/or basis;
- Related party (“RP”) = means:
- a Material Shareholder (10% + for prime segment and 20% for general segment);
- CEO and/or directors (or persons acting with the same authority) of the ListCo or of ListCo’s holding company H Co – currently or in the last 12 months (“Group Directors”);
- any adviser that has, or had, in the last 12 months a beneficial interest in ListCo or in any ListCo Associate;
- a prescribed officer of ListCo;
- any person included in the definition of “extended family” being:
- parents plus spouses;
- siblings plus spouses; and
- major children plus spouses of Group Directors and his/her spouse.
- the asset manager or management company (“Manco”) (collectively “Managers”) of a listed Property Entity or Investment Entity, and the Managers controlling shareholders, and any person whose assets the Managers manage;
- any Associates of the above.
- RP Trans = an agreement between a ListCo group (ListCo and/or SubCo) and:
- a RP; or
- another person acting on behalf of or for the benefit of a RP;
in respect of:
- an acquisition (“acq”) or disposal (“disp”); or
- any other agreement.
- RP Trans ITOCOB = a RP Trans ITOCOB between a RP (excluding a ListCo or ListCo’s holding company (“H Co”) director and/or associates);
- RP Trans ITOCOB (RP = directors/associates) = a RP Trans between a RP (where the RP is a director and/or associates of a director of ListCo or H Co) and a ListCo group;
- ITOCOB = in the ordinary course of business, requiring JSE approval after having regard to the following:
- nature of business of ListCo and the transacting party;
- incidence of similar transactions concluded;
- size measured against similar transactions concluded;
- whether the transaction contributes to ListCo’s “normal” revenue;
- whether the transaction contributes to costs related to “normal” revenue;
- whether the transaction constitutes ITOCOB for ListCo and the other transacting party; and
- Public = public shareholders, defined by excluding shareholders of ListCo that are considered to be non‑public persons, as follows:
- directors of ListCo and/or of any ListCo major SubCos and their associates;
- associates of ListCo and/or of major SubCos;
- extended family of a ListCo director;
- trustees of ListCo group share incentive schemes or of ListCo group pension funds;
- prescribed officers of ListCo;
- ListCo controlling shareholders; and
- any person with trading restrictions over ListCo securities for a period >six months from the listing date.
- RTO = reverse takeover requirements detailed in Section 8, being an acquisition of an asset(s) satisfying the following criteria:
- a Cat 1 acquisition categorisation percentage (“Cat %”) =/>100%; and
- the acquisition will result in one or more of the following:
- a fundamental change in the business, being the acquisition of a business that – comprises the majority of all future business (>50%); and/or
- a change in Board control (being 35% or more control of Board votes); and/or
- a change in shareholder voting control (being 35% or more of entitled votes cast in GM/AGM).Aggregation compliance =
- aggregation of a series of transactions detailed in Section 8 that have the following asset subject matter compliance requirements:
- the same asset acquired/disposed of on a piecemeal basis over time; and/or
- different assets acquired/disposed of from/to the same vendor/emptor; and/or
- different assets acquired from different vendors/emptors (but) in respect of the same new substantial (30%+ of market cap) business segment;
- the time period applicable to the series of the asset(s) transactions is a “look back” period of 12 months from the date of agreement of the current transaction, therefore any transaction older than 12 months will “drop out” of the aggregation series;
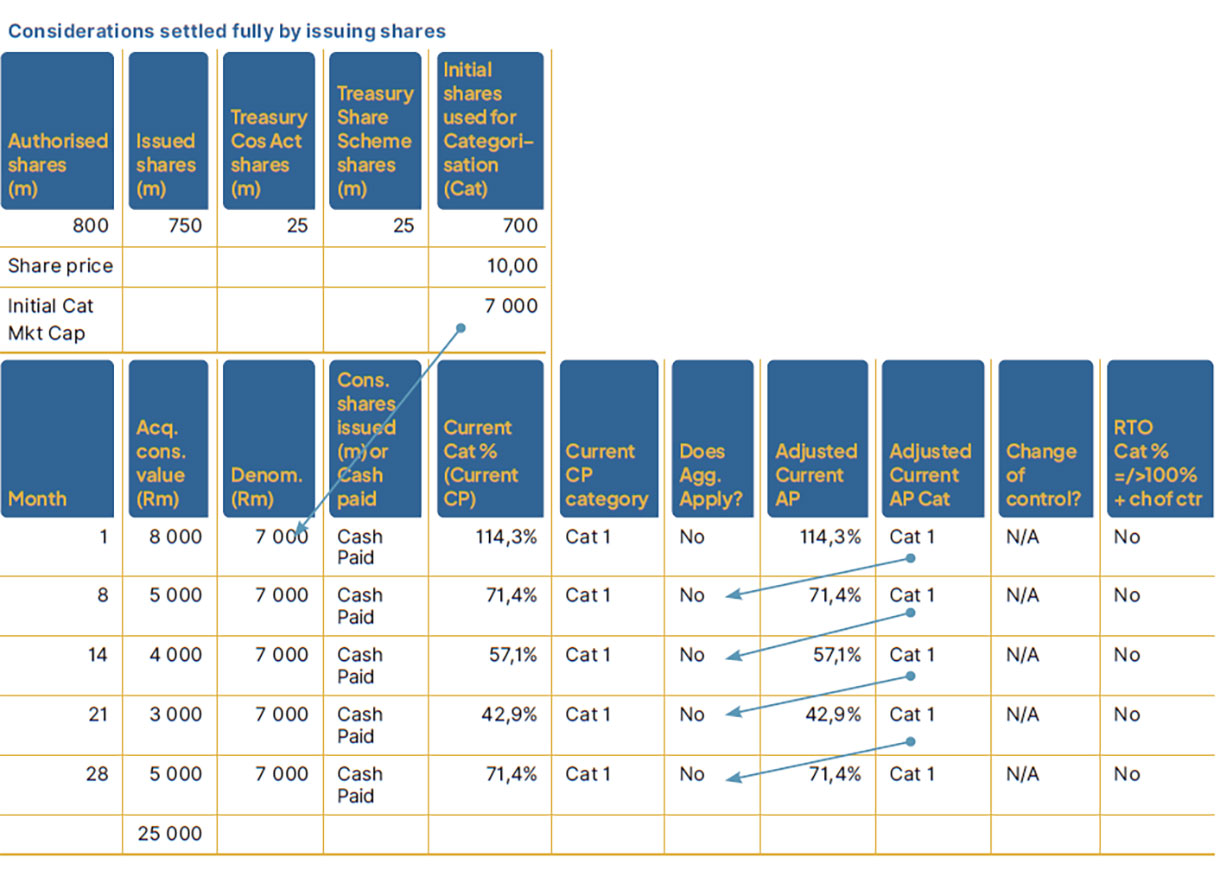
- for each current transaction calculate the categorisation percentage (“Current CP”);
- if aggregation applies, add the previously calculated categorisation percentage(s) (“Previous CP”) to the Current CP, thereby calculating the aggregation percentage for the current transaction (“Current AP”);
- if any of the Previous CP were Category 1 transactions, they are excluded from the Current AP which results in a subtraction of such percentage(s) from the Current AP, resulting in a lower Current AP for categorisation purposes, resulting in an “Adjusted Current AP”, which is used as the final categorisation percentage;
- notwithstanding the subtraction of previous Category 1 transaction(s) from the Current AP, the Current AP must be used to determine whether a RTO has resulted from such Current AP, and if it has, (then) the RTO requirements must be complied with, resulting in a JSE review of the continued listing of ListCo and the issue of RLP.
The following tables illustrate the aggregation calculations regarding a series of five acquisitions (in the same line of business as ListCo, therefore not giving rise to a fundamental change of business) over a period of 28 months for a total consideration (at fair value) of R25bn with regard to settlement of the consideration being firstly, in shares and secondly, in cash. The aggregation examples illustrate the new RTO requirements in the JSE LR.

Corporate Actions tables
All CAs must comply with the relevant timetable contained in Schedule H to the JSE LR. CAs with an entitlement require last day to trade ("LDT"), record date ("RD") and pay date ("PD").
Table content applies to both the prime segment and general segment unless indicated by way of a footnote explaining the deregulation applicable to the general segment.
| Cash Dividend | |||
| CA description | Pro rata payment of cash to shareholders from retained income | ||
| JSE approval required | Directors' approval only unless MOI requires shareholder approval ("Director or Sh/h Approval") | ||
| Sponsor approved Results Announcement of declaration required in IFS/Second IFS (SENS and press), Cond AFS (SENS and press) or Cons AFS (SENS) ("Results Announcement") | |||
| Circular if Sh/h Approval required ("Circular Required") | |||
| If Sh/h Approval required = OR >50% all vote | |||
| Timetable – last date to trade ("LDT"), record date ("RD") and payment date ("PD") applicable | |||
| No PLS/RLP or WCS or FO required | |||
| Cos Act approval required | As per JSE approval above | ||
| SLT passed |
| Scrip Dividend | |||
| CA description | Pro rata payment to shareholders of cash dividends with an alternate election to receive capitalisation issue shares ("cap issue") | ||
| JSE approval required | Directors’ or Sh/h Approval | ||
| Results Announcement – refer to Cash Dividend – will also provide volume weighted average price (“VWAP”) pricing for cap issue shares | |||
| Circular Required – dealing with election of cash or shares | |||
| If Sh/h Approval required = OR >50% all votes | |||
| Timetable – LDT, RD and PD applicable | |||
| No PLS/RLP or WCS or FO required | |||
| Cos Act approval required | As per JSE approval above | ||
| SLT passed for cash portion | |||
| If increase of authorised shares required = SR 75%+ all vote MOI amendment required = SR 75%+ all vote | |||
| (“Increase of Authorised Shares Required”) | |||
| If shares are par value and Increase of Authorised Shares Required = requires conversion of par value shares to no par value shares before authorised share increase = SR 75%+ all vote | |||
| MOI amendment required = SR 75%+ all vote | |||
| (“Convert PV to NPV Required”) | |||
| If =/> 30% voting shares to be issued = SR 75%+ all vote required in terms of Section 41(3) (“30% Section 41(3) Rule Required”) |
| Capitalisation issue ("cap issue") | |||
| CA description | Pro rata issue of capitalisation shares to shareholders for no consideration | ||
| JSE approval required | Directors' or Sh/h Approval | ||
| Announcement required (SENS and press) ("Announcement Required") | |||
| Circular required only if MOI requires shareholder approval | |||
| If shareholder approval required = Ordinary Resolution >50% all vote | |||
| Timetable – LDT, RD and PD applicable | |||
| No PLS/RLP or WCS or FO required | |||
| Cos Act approval required | As per JSE approval above | ||
| No SLT required | |||
| If Increase of Authorised Shares Required – refer to Scrip Dividend above | |||
| If Convert PV to NPV Required – refer to Scrip Dividend above | |||
| If 30% Section 41(3) Rule Required – refer to Scrip Dividend above |
| Rights Offer (“RO”) – renounceable | |||
| CA description | Pro rata issue of shares to shareholders for a cash consideration per share | ||
| JSE approval required | Directors’ Approval required to proceed with RO, approve Rights Offer price (should be at a reasonable discount to recent share price) and determine whether excess applications are allowed | ||
| Announcement Required | |||
| Circular Required – contains all Rights Offer details | |||
| Listing of letters of allocation (“LAs”) | |||
| Timetable – LDT, RD and PD applicable | |||
| No PLS/RLP or WCS or FO required | |||
| Cos Act approval required | As per JSE approval above – circular content also satisfies Cos Act | ||
| No SLT required | |||
| If Increase of Authorised Shares Required – refer to Scrip Dividend above | |||
| If Convert PV to NPV Required – refer to Scrip Dividend above | |||
| If 30% Section 41(3) Rule Required – refer to Scrip Dividend above | |||
| Takeover Law | If subscription or underwriting results in a Controlling Shareholder emerging = Mandatory Offer required unless Waiver Approval obtained before proceeding with the RO (if Controlling Shareholder emerges, Mandatory Offer or Waiver Approval required) | ||
| Rights Offer – non-renounceable | |||
| CA description | Pro rata issue of shares to shareholders for a cash consideration per share | ||
| JSE approval required | Directors’ Approval required | ||
| Maximum discount is 10% to the 30-day VWAP | |||
| Announcement Required (SENS and press) | |||
| Circular – contains all rights offer details | |||
| LAs listed but trading suspended i.e. no sale/purchase of LAs allowed | |||
| Timetable – LDT, RD and PD applicable | |||
| No PLS/RLP or WCS or FO required | |||
| Cos Act approval required | As per JSE approval above – circular content also satisfies Companies Act | ||
| No SLT required | |||
| If Increase of Authorised Shares Required – refer to Scrip Dividend above | |||
| If Convert PV to NPV Required – refer to Scrip Dividend above | |||
| If 30% Section 41(3) Rule Required – refer to Scrip Dividend above | |||
| Takeover Law | If Controlling Shareholder emerges, Mandatory Offer or Waiver Approval required | ||
| Specific IFC ("Specific IFC") to a non-RP – accelerated Specific IFC to non-RP = same | |||
| CA description | Biased subscription issue of any number of shares or options/convertible securities ("opcons") to any non-RP person at any price to raise cash or to settle a monetary liability or monetary expense (Unlimited Specific IFC to non-RP) | ||
| JSE approval required | Directors' Approval to proceed and approve subscription price (usually at a discount to reference price) | ||
| Announcement Required | |||
| Circular – contains all Specific IFC details | |||
| If issue > 1/4% of the number of issued shares or subscription price is at a discount to 30 bd VWAP (“30 bd VWAP Discount”) = OR >50% ind votes (> 1/4% and/or Discount = OR >50% ind vote) | |||
| If opcons strike price is >10% discount to the 30 bd VWAP (“>10% Discount to 30 bd VWAP”) = iNED FO | |||
| Timetable | |||
| No PLS/RLP or WCS or FO required | |||
| Cos Act approval required | As per JSE approval above – circular content also satisfies Companies Act | ||
| No SLT required | |||
| If Increase of Authorised Shares Required – refer to Scrip Dividend above | |||
| If Convert PV to NPV Required – refer to Scrip Dividend above | |||
| If 30% Section 41(3) Rule Required – refer to Scrip Dividend above | |||
| Takeover Law | If Controlling Shareholder emerges, Mandatory Offer or Waiver Approval required | ||
| Specific IFC to a ListCo director (“director RP”) | |||
| CA description | Unlimited Specific IFC to a director RP | ||
| JSE approval required | Directors’ Approval to proceed and approve subscription price | ||
| Announcement Required | |||
| Circular – contains all Specific IFC details | |||
| > 1/4% and/or Discount to the 30 bd VWAP = OR >50% ind Vote | |||
| If Specific IFC is to RP and issue price = Discount to the 30 bd VWAP = iNED FO | |||
| If opcons strike price is >10% Discount to 30 bd VWAP Discount = iNED FO | |||
| Timetable | |||
| No PLS/RLP or WCS required | |||
| Cos Act approval required | As per JSE approval above – circular content also satisfies Companies Act | ||
| No SLT required | |||
| If Increase of Authorised Shares Required – refer to Scrip Dividend above | |||
| If Convert PV to NPV Required – refer to Scrip Dividend above | |||
| If 30% Section 41(3) Rule Required – refer to Specific IFC above | |||
| If securities issued to a director, prescribed officer or related person = SR 75%+ all votes required in terms of Section 41(1) (“Section 41(1) Rule Required”) |
|||
| Takeover Law | If Controlling Shareholder emerges, Mandatory Offer or Waiver Approval required | ||
| Specific IFC to a material shareholder5 (“RP”) | |||
| CA description | Unlimited Specific IFC to a material shareholder5 (RP) | ||
| JSE approval required | Directors’ Approval to proceed and approve subscription price (“Discount”) | ||
| Announcement required | |||
| Circular – contains all Specific IFC details | |||
| > ¼% and/or Discount to the 30 bd VWAP = OR >50% ind vote | |||
| If Specific IFC is to RP and issue price = Discount to the 30 bd VWAP = iNED FO | |||
| If opcons strike price is >10% Discount to 30 bd VWAP Discount = iNED FO | |||
| Timetable | |||
| No PLS/RLP or WCS required | |||
| Cos Act approval required | As per JSE approval above – circular content also satisfies Companies Act | ||
| No SLT required | |||
| If Increase of Authorised Shares Required – refer to Scrip Dividend above | |||
| If Convert PV to NPV Required – refer to Scrip Dividend above | |||
| If 30% Section 41(3) Rule required – refer to Specific IFC above | |||
| Takeover Law | If Controlling Shareholder emerges, Mandatory Offer or Waiver Approval required | ||
| Accelerated Specific IFC to an RP | |||
| CA description | Unlimited Specific IFC to a RP | ||
| JSE approval required | Directors’ Approval to proceed and approve subscription price | ||
| Announcement Required | |||
| Circular – contains all Specific IFC details – JSE approval time is only 48 hours | |||
| > ¼% and/or Discount to the 30 bd VWAP = OR >50%+ ind vote | |||
| Must be an issue for “cash” – opcons may not be issued | |||
| If issue is to RP = no discount to 30 bd VWAP is allowed | |||
| Timetable – saves eight bd of JSE approval time – rest of timetable is the same | |||
| No PLS/RLP or WCS required | |||
| Cos Act approval required | As per JSE approval above – circular content also satisfies Companies Act | ||
| No SLT required | |||
| If Increase of Authorised Shares Required – refer to Scrip Dividend above | |||
| If convert PV to NPV required – refer to Scrip Dividend above | |||
| 30% Section 41(3) Rule Required = already in effect = not allowed as part of the CA | |||
| Section 41(1) Rule Required is not allowed | |||
| Takeover Law | If Controlling Shareholder emerges, Mandatory Offer or Waiver Approval required | ||
| General IFC (“General IFC”) | |||
| CA description | Biased subscription issue of a limited number of listed shares or opcons to public shareholders/persons (“Public Persons”), or Public Persons and RPs via a bookbuild mechanism, at a limited discount price to raise cash or to settle a liability or expense during the Approval Period | ||
| JSE approval required | Initial General IFC shareholder approval required in AGM (or special GM) (General IFC Authority) = OR 50% all vote – approval expires at next AGM or after 15 months (“Approval Period”)1 | ||
| Number of securities or opcons that may be issued limited to <30% of number of securities in issue (and listed) at date of giving Notice of AGM (or special GM) (“Base Number”)1 | |||
| Subscription price or strike price of opcons limited to a maximum 10% discount to 30 bd VWAP at (each) date of issue – there may be many different issues in Approval Period | |||
| Each issue may only be made to Public Persons, however, RPs may participate in a General IFC that is effected by way of a bookbuild process provided the RP is a price taker and not a price maker. Expanded SENS disclosure required | |||
| Directors’ Approval required to proceed with each issue (usually at a discount) | |||
| Announcement Required – for all issues that reach 5% of the Base Number and thereafter | |||
| Circular approval required or circular content included in Notice of AGM | |||
| Timetable | |||
| No PLS/RLP or WCS required | |||
| Cos Act approval required | As per JSE approval above – circular content also satisfies Companies Act | ||
| No SLT, no Section 41(1) Rule Required and no Section 41(3) Rule Required | |||
| If Increase of Authorised Shares Required – refer to Scrip Dividend above – effect in AGM | |||
| If Convert PV to NPV Required – refer to Scrip Dividend above – effect in AGM | |||
| Takeover Law | If Controlling Shareholder emerges, Mandatory Offer required or Waiver Approval required | ||
| Specific ROS (by ListCo from a non–RP shareholder) | |||
| CA description | Biased ROS of ListCo shares by ListCo from any non-RP ListCo shareholder at any price | ||
| JSE approval required | Directors’ Approval required to proceed | ||
| Shareholder approval not required for pro rata ROS (reverse rights offer) or intra-group ROS (ListCo acquires ListCo securities from SubCo or from any Share Incentive Scheme) (“Shareholder Approval Exemption”) | |||
| Shareholder approval required = OR >50% ind votes (until amended or revoked by OR >50% ind votes) subject to Shareholder Approval Exemption2 | |||
| Number of shares unlimited subject to Companies Act compliance requiring =/>1 equity share in issue | |||
| ROS price unlimited | |||
| ROS made from a non‑RP shareholder in this example | |||
| Announcement Required | |||
| Circular approval required | |||
| Timetable | |||
| SLT required but no FO | |||
| Cos Act approval required | As per JSE approval above | ||
| SLT required | |||
| Repurchased shares “issue” status cancelled in terms of Section 35 (“Issue Status Cancelled”) | |||
| If ListCo or SubCo(s) provide(s) a loan(s) to ListCo or SubCo(s) to fund a ROS of ListCo shares = Section 44 requires compliance = SR 75%+ all vote – plus – SLT – plus – F+R by the Board (“Section 44 Compliance Required”) | |||
| If SubCo(s) provide a loan(s) to ListCo or other SubCo(s) to fund a ROS of ListCo shares = Section 45 requires compliance = SR 75%+ all vote – plus – SLT – plus – F+R by the Board (“Section 45 Compliance Required”) | |||
| Takeover Law | If a non‑participating shareholder becomes a Controlling Shareholder as a result of increased voting power arising from a repurchase from other shareholders, a Mandatory Offer must be made e.g. 34.9% moves to 36.7% if 4.9% repurchased from other shareholders (“if Controlling Shareholder emerges, Mandatory Offer required”) | ||
| Specific ROS of </= 10% of ListCo Shares by ListCo’s SubCo(s) from a non‑RP shareholder | |||
| CA description | Biased ROS of ListCo shares by ListCo’s SubCo(s) from any non‑RP ListCo shareholder at any price | ||
| JSE approval required | Directors’ Approval of ListCo and SubCo required to proceed | ||
| Shareholder approval required = OR >50% ind votes (until amended or revoked by OR >50% ind votes) subject to Shareholder Approval Exemption2 | |||
| Number of shares limited to </= 10% of ListCo’s issued securities | |||
| ROS price unlimited | |||
| ROS made by ListCo’s SubCo from a non‑RP shareholder | |||
| Announcement Required | |||
| Circular approval required | |||
| Timetable | |||
| SLT required but no FO | |||
| Cos Act approval required | As per JSE approval above | ||
| SLT required | |||
| Repurchased shares issued status is not Cancelled i.e. remain in issue in terms of Section 35 and Section 48 (“Issued Status Not Cancelled”) | |||
| Repurchased shares have no voting power whilst SubCo remains a SubCo in terms of Section 48(2) and are titled “treasury shares” (“No Voting Power”) | |||
| If Section 44 Compliance Required – refer to Specific ROS from a non‑RP sh/h above | |||
| If Section 45 Compliance Required – refer to Specific ROS from a non‑RP sh/h above | |||
| Takeover Law | If Controlling Shareholder emerges, Mandatory Offer required | ||
| Specific ROS of ListCo Shares by ListCo from an RP shareholder | |||
| CA description | Biased repurchase of ListCo shares by ListCo from an RP shareholder (either a ListCo director or material shareholder5) at any price | ||
| JSE approval required | Directors’ Approval required to proceed | ||
| Shareholder approval required = OR >50% ind votes (until amended or revoked by OR >50% ind votes) subject to Shareholder Approval Exemption | |||
| Number of shares unlimited subject to Companies Act compliance requiring =/>1 equity share in issue | |||
| ROS price unlimited | |||
| ROS made by ListCo from an RP shareholder in this example | |||
| Announcement required | |||
| Circular approval required | |||
| iNED FO required if price = premium to 30 bd VWAP | |||
| Timetable | |||
| SLT required | |||
| Cos Act approval required | As per JSE approval above | ||
| SLT required | |||
| Issue Status Cancelled | |||
| If Section 44 Compliance Required – refer to Specific ROS from a non‑RP sh/h above | |||
| If Section 45 Compliance Required – refer to Specific ROS from a non‑RP sh/h above | |||
| Takeover Law | If Controlling Shareholder emerges, Mandatory Offer required | ||
| Specific ROS of </= 10% of ListCo Shares by ListCo’s SubCo(s) from an RP shareholder | |||
| CA description | Biased ROS of ListCo shares by ListCo’s SubCo(s) from an RP shareholder (ListCo director or material shareholder6) at any price | ||
| JSE approval required | Directors’ Approval of ListCo and SubCo required to proceed | ||
| Shareholder approval required = OR >50% ind votes (until amended or revoked by OR >50% ind votes) subject to Shareholder Approval Exemption | |||
| Number of shares limited to </= 10% of ListCo’s issued securities | |||
| ROS price unlimited | |||
| ROS made by ListCo’s SubCo from an RP shareholder6 | |||
| Announcement required | |||
| Circular approval required | |||
| iNED FO required if price = premium to 30 bd VWAP | |||
| Timetable | |||
| SLT required | |||
| Cos Act approval required | As per JSE approval above | ||
| SLT required | |||
| Issued Status Not Cancelled but have No Voting Power | |||
| If Section 44 Compliance Required – refer to Specific ROS from a non‑RP sh/h above | |||
| If Section 45 Compliance Required – refer to Specific ROS from a non‑RP sh/h above | |||
| Takeover Law | If Controlling Shareholder emerges, Mandatory Offer required | ||
| General ROS by ListCo or ListCo’s SubCo | |||
| CA description | Biased ROS of ListCo shares by ListCo or up to 10% of ListCo shares by ListCo’s SubCo – both through the secondary market | ||
| JSE approval required | Directors’ Approval of ListCo and SubCo required to proceed | ||
| Initial shareholder approval required in AGM (or special GM) = OR >50% all votes – approval expires at next AGM or after 15 months (Approval Period) subject to Shareholder Approval Exemption3 | |||
| Number of shares limited to 20% per FYE – this is limited to </= 10% for ListCo’s SubCo(s) – dictated by the Companies Act | |||
| Repurchase price limited to a 10% premium to the five bd VWAP | |||
| Repurchases are made through the secondary market therefore no knowledge of who selling shareholder is – therefore no concern with RP shareholders selling | |||
| Announcement required (SENS and press) for each 3% threshold reached | |||
| Circular approval required or circular content included in Notice of AGM | |||
| Repurchases during PP, including convening a GM, are prohibited unless a programme is submitted to the JSE detailing the number of securities to be repurchased over a period of time outside of a PP by a named independent stockbroker that proceeds to repurchase the securities on an independent basis (“PP Prohibition or Programme Exemption Compliance Required”) | |||
| Timetable | |||
| SLT required | |||
| Cos Act approval required | As per JSE approval above | ||
| SLT required | |||
| ListCo ROS = Issued Status Cancelled but SubCo(s) ROS = Issued Status Not Cancelled but have No Voting Power | |||
| If Section 44 Compliance Required – refer to Specific ROS from a non‑RP sh/h above | |||
| If Section 45 Compliance Required – refer to Specific ROS from a non‑RP sh/h above | |||
| Takeover Law | If Controlling Shareholder emerges, Mandatory Offer required | ||
| Payment to Shareholders | |||
| CA description | Capital payment of cash or assets to ListCo shareholders by ListCo | ||
| JSE approval required | Directors’ Approval to proceed | ||
| Payment is of cash or assets as a capital payment from share capital, share premium or stated capital to shareholders | |||
| If payment is made pro rata and for cash or listed securities, no shareholder approval required | |||
| If payment is non-pro rata and/or is non‑cash and/or is non‑listed securities – shareholder approval required = OR >50% all vote | |||
| Announcement required (SENS and press) – all details | |||
| Circular approval required | |||
| Timetable – LDT, RD and PD applicable | |||
| SLT required | |||
| Cos Act approval required | As per JSE approval above | ||
| SLT required as this is a capital distribution | |||
| Takeover Law | Not applicable | ||
| Odd Lot Offer | |||
| CA description | Offer and expropriation mechanism made by a third party or by ListCo or ListCo’s SubCo to ListCo shareholders holding an odd lot of ListCo shares | ||
| JSE approval required | Directors’ Approval of ListCo and SubCo required to proceed | ||
| Mechanism is an offer to acquire odd lots and if shareholders elect not to sell, they retain the odd lot holding – if shareholders do not elect the odd lot holdings are expropriated i.e. forced selling | |||
| Mechanism may be effected as a third-party offer or as an ROS | |||
| Odd lot holding default definition = between 1 and 99 shares – but the 99 may be increased based on breakeven trading cost | |||
| Shareholder approval required = OR >50% ind vote – if effected using a repurchase mechanism – refer to ROS CAs | |||
| Shareholder approval also required for the odd lot CA itself = OR > 50% ind vote (“Odd Lot OR”) | |||
| MOI amended to provide for the Odd lot OR if MOI does not include such clause | |||
| Offer price = market price or premium thereto plus all costs | |||
| Announcement required (SENS and press) – all details | |||
| Circular approval required | |||
| PP Prohibition or Programme Exemption Compliance Required if effected as a General ROS – not required if effected as a Specific ROS or third‑party offer | |||
| Timetable – LDT, RD and PD applicable | |||
| SLT required if effected as a ROS | |||
| Cos Act approval required | As per JSE approval above | ||
| Refer to ROS CAs for required compliance | |||
| Takeover Law | If Controlling Shareholder emerges, Mandatory Offer required | ||
| Panel approval required as this is a split class offer | |||
| Alteration of Capital | |||
| CA description | Per security class – creation of a new class, variation of rights, conversion from PV to NPV, increase of authorised share capital, subdivision, consolidation, cancellation | ||
| JSE approval required | Directors’ approval of ListCo | ||
| Shareholder approval required = Special Resolution 75%+ all votes | |||
| Announcement required (SENS and press) – all details | |||
| Circular approval required | |||
| Timetable – LDT, RD and PD applicable | |||
| No WCS or FO required | |||
| Cos Act approval required | As per JSE approval above | ||
| If Increase of Authorised Shares Required – refer to Scrip Dividend above | |||
| If Convert PV to NPV Required – refer to Scrip Dividend | |||
| Amendment of MOI required | |||
| Takeover Law | Not applicable | ||
| Acquisitions and Disposals | |||
| CA description | Acquisition or disposal of assets (“acq/disp”) by ListCo or ListCo’s SubCo(s) | ||
| JSE approval required | Directors’ approval of ListCo | ||
| Categorisation percentage (“Cat %”) is determined by dividing consideration receivable/payable by adjusted market cap (excl. treasury shares) or by dividing acq shares issued by adjusted ListCo shares in issue (excl. treasury shares) resulting in a percentage that is then used for categorisation (“Cat”) | |||
| Arm’s length acq/disp involves non-RP acq/disp | |||
| Arm’s length acq/disp categorisation percentages and compliance = | |||
|
|||
|
|||
|
|||
|
|||
|
|||
|
|||
|
|||
|
|||
|
|||
|
|||
| Not ITOCOB Aggregation rules apply to piecemeal RP acq/disp </=1/4% effected over a rolling 12-month period = resulting in small RP transaction compliance | |||
| RTO = reverse takeover – refer to RTO in the Commentary and Legend | |||
| Issue of ListCo shares =/> 50%4 for an acq requires RLP to be issued | |||
| Timetable | |||
| If a vendor sells assets to ListCo and requires cash settlement – ListCo may issue ListCo shares for cash at up to a 10% discount to a three bd or 30 bd VWAP to any persons and use the subscription cash to settle the vendor (“vendor placement”) | |||
| WCS required for all Cat 1 transactions | |||
| Cos Act approval required | As per JSE approval above | ||
| No SLT required | |||
| If Increase of Authorised Shares Required – refer to Scrip Dividend above | |||
| If Convert PV to NPV Required – refer to Scrip Dividend above | |||
| If disp >50% of fair value gross assets/undertaking = Section 112 compliance – requires IPEx F+RO and sh/h approval = SR 75%+ ind vote | |||
| Takeover Law | If Controlling Shareholder emerges, Mandatory Offer required or Waiver Approval obtained | ||
| Voluntary Delisting | |||
| CA description | Delisting of ListCo shares from the JSE on a voluntary basis | ||
| JSE approval required | Directors’ approval of ListCo | ||
| Shareholder approval required = OR 75%+ ind vote (excludes the offeror, offeror associates and offeror concert parties) | |||
| An offer must be made to all ListCo shareholders by a person – either ListCo as a repurchase offer or a third‑party offer | |||
| An IPEx F+RO is required, and the opinion must be “fair and reasonable” | |||
| Announcement required (SENS and press) – all details | |||
| Circular approval required | |||
| Timetable – LDT, RD and PD applicable | |||
| No WCS required | |||
| Cos Act approval required | As per JSE approval above | ||
| Takeover Law | The offer required by the JSE is a General Offer in terms of Takeover Law and must comply with all Takeover Law requirements | ||
| General segment exemptions | |
| 1 | No General IFC authority required from sh/h provided any General IFC is </=10% of number of shares in issue at date of AGM and complies with all other General IFC authority requirements (Approval Period, listed securities, opcons, Public Persons or Public Persons and RPs via a bookbuild, maximum 10% issue price discount to 30 bd VWAP). |
| 2 | Specific ROS from non‑RPs does not require shareholder approval provided number of securities repurchased =/<20% in any one FYE. |
| 3 | General ROS authority from shareholders not required for General Segment but compliance required for all other General ROS authority requirements (Approval Period, maximum 10% price premium to five bd VWAP, ROS number </= 20% per FYE exc treasury shares, ROS effected through JSE order book, PP Prohibition or Programme Exemption Compliance Required, 3%+ Announcement Required). |
| 4 | Rolling month period acquisition issues requiring a PLS/RLP increased to 100% from 50%. |
| 5 | Cat 2 =/> 5% to < 50% and Cat 1 =/> 50%. |
| 6 | Material shareholder definition (RP) increased to =/> 20% from 10%. |
| 7 | Small RP transaction >3% to </= 10%. |
| 8 | ITOCOB exemption is <50%. |